HOLIDAY DISCOUNT — 20% OFF CARDS THROUGH NOVEMBER 1628 DAYS LEFT Questions? 833-682-8250  ·  [email protected]
Best Holiday CardsPublishing greeting cards
since 2003

Business Holiday Cards  ·  Mortgage Brokers, Banks & Credit Unions

Holiday Cards for Lenders — the closing table was the beginning, not the end

Mortgage brokers, loan officers, community banks, credit unions. Businesses where one transaction is supposed to start a twenty-year relationship — and usually doesn't.

100 cards$2.85under, per card
250 cards$2.35under, per card
500 cards$2.18under, per card
1,000 cards$1.85under, per card
2,500 cards$1.75under, per card
5,000 cards$1.64under, per card
10,000 cards$1.60under, per card

Good-tier pricing, with envelopes and imprinting included. Early-order discounts come off on top of these prices — 20% by November 16, 10% by December 11. Better and Best designs cost more — see all three tiers and price your order.

Five years of silence is the industry standard

You sat with them through the most nerve-racking financial hour of their life, you got it closed, and then the file went quiet. Five, six, seven years until the next move or the next refinance. When rates turn, the call goes to whoever they heard from most recently. That is almost never the person who did the loan.
Your referral partners outvalue your borrowers

Realtors, title agents, insurance agents, CPAs, builders, attorneys — that list is short, it is worth more per name than any borrower list you have, and it is the list most often left off the card order. A card from you sits on a realtor's office wall through the exact months they are deciding who to send the next buyer to.

Community is the whole pitch — print it

A credit union or a community bank is selling one thing a national lender can't fake: we are from here. Our US Regions family puts the place on the card. It is a small move and members notice it, because the alternative arriving in their mailbox is a card that could have come from anywhere.

When to send

Getting the timing right for Lenders

Volume is the point in this business, and volume is where the per-card price starts working for you. That means the list is big, the addressing is real work, and December is not when you want to discover either. Order in September, mail before Thanksgiving. A borrower who hears from you once a year, warmly and with nothing attached, is the one who calls you instead of a rate table when the market moves. The early-order discount takes 20% off the card price if you order by November 16, then 10% by December 11.

Cards for lenders

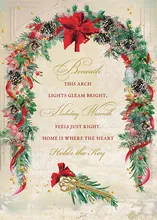
Key to your Heart is the closing card — greenery over a doorway and the key to a newly sold home. The rest work for a branch or a book. Prices shown are per card with envelopes at 100 — they come down at every quantity break.

Three designs, picked by a person

Not sure which design fits your list?

Tell us who you’re sending to and roughly how many. We’ve been publishing cards since 2003 — we’ll come back with three that actually fit, and you take it from there. No obligation, and we don’t hand your address to anybody.

We answer every one, usually the same business day. Prefer to browse first? The whole catalog is here.

What to write inside

Wording that works for Lenders

A mortgage is a seven-year relationship that feels like a sixty-day one. The card is what makes it the first thing.

“Thank you for letting us help with your home this year. Wishing you a wonderful holiday in it.”

This year’s closings. It ties the card to the biggest thing that happened to them all year.

“Thank you for your business and your trust. We are here whenever you or someone you know needs us.”

Past borrowers. Refinance and referral both live in that second sentence.

“We appreciate the opportunity to serve you and your family. Best wishes for the season.”

Banks and credit unions — institutional, safe across a whole member list.

“Thank you for sending your clients our way this year. The partnership means a great deal.”

For realtors, builders and the referral partners who feed the pipeline.

Up to four lines on the card and four on the envelope, in a coordinated ink color and any of about a hundred font styles. Imprinting is free, always — it is not a seasonal promotion.

Getting it right

Three things worth getting right

No rates, no products, no “now is a great time”

The moment a number appears, the card becomes an advertisement and inherits every disclosure rule that comes with one. Keep it clean.

Know which entity is signing

Loan officer, branch, bank, credit union — they are not interchangeable on client-facing mail, and your compliance group has a view. Settle it before you order.

Referral partners are a separate list

The realtor who sends you six files a year should not get the same card as the borrower who closed once in 2019. She is worth her own design.

Design families to browse

The categories lenders order from most. Prices are per card with envelopes at 1,000.

See all 370+ designs

Questions we get from lenders

What do you write in a holiday card to past borrowers?
Nothing about rates. “It was good to work with you this year” or simply a thank you and the year — that's the whole card. The temptation is to add a line about refinancing, and that line is what turns a greeting into an ad and gets it thrown out. Trust the card to do its job, which is to keep your name in the house until the day they need it.
Should the card come from the loan officer or the institution?
The person, with the institution behind it. Borrowers remember a name and a voice, not a logo — and if they can't remember the name, the card has done half a job. We imprint up to four lines, so the branch or company name, the officer's name and a short greeting all fit comfortably. Banks and credit unions with multiple branches usually run one design and vary the imprint by location.
Is a holiday card considered advertising?
We print cards, we are not your compliance officer — that call belongs to whoever handles it for you. The general principle lenders work from: keep rates, payment amounts, terms and any offer off the card entirely, and what's left is a greeting rather than an advertisement. Whether to carry an NMLS ID is a question for your compliance officer too. Many loan officers include it out of habit and it costs you nothing to imprint.
How many should a loan officer order?
Borrowers from the last five years, plus every referral partner, plus your current pipeline. For most individual loan officers that's 200 to 500. For a branch it runs into the thousands, and that's where the per-card price starts working for you — $1.85 a card with envelopes at 1,000, before the early-order discount.

Not sure where to start?

Tell us who you're sending to and roughly how many. We've been doing this since 2003 — we'll point you at the three or four designs that actually fit, and you can take it from there.

Browse the catalog Talk to a person